The certificate arrived by email the night before the crew was due, was opened, glanced at, and filed without much more thought. It looked official enough — a policy number and a couple of coverage limits sat above a signature near the bottom. What it had not established was whether that policy was still active, whether it actually covered the work about to happen, or whether the business named on it was the same one sending a truck up the driveway the next morning.
If something goes wrong while that crew is on the property, the question that actually matters is whose policy answers for it. A document glanced at once rarely settles that on its own.

Who Pays When the Crew Causes the Damage
The loss in question happens while the crew is on the clock: a section dropped off its intended line into a fence or a window, a rigging line that gives way, a truck parked where it shouldn’t be, a worker injured while working. This is damage caused by the work a homeowner hired someone to do, distinct from whatever the tree itself might do through age, lean, or a storm.
Most homeowners assume the contractor’s own insurance handles this automatically, and in a straightforward case, it does. That assumption is only as good as the policy behind it. A crew can be underinsured, insured for the wrong kind of work, or insured under a business name that no longer matches the one on the invoice. None of that becomes visible until a claim is filed, and by then the coverage either answers or it doesn’t. The contractor’s insurance is the mechanism that decides who absorbs a loss that has already happened.
Two Policies that Answer Two Different Questions
Two separate kinds of coverage sit behind a tree crew, and they answer two different questions. General liability responds to damage — a struck fence, a parked car, a section of roof taken out by a falling limb. Workers’ compensation responds to a person: a crew member injured while working on the property, whether from a fall, equipment, or a limb that came down wrong.
Homeowners tend to ask about the first and forget the second exists, largely because the first protects something they can see and the second protects someone they may never have thought about. A contractor can genuinely hold one without the other. Sole operators and very small crews are the common case where workers’ compensation is thin or missing entirely, since it is the coverage most often skipped to keep a quote competitive. When a contractor holds one but not the other, the injury exposure has nowhere to land inside the contractor’s own cover — a gap that surfaces only once someone is actually hurt. Equipment coverage is worth naming only to set it aside: it protects the contractor’s chipper or bucket truck, and it answers for neither a fence nor an injured worker.
The distinction is not obscure once it is stated plainly, and the Insurance Information Institute publishes plain-language explanations of the difference between liability coverage and workers’ compensation.
What a Certificate of Insurance Actually Proves
A certificate of insurance is a summary, issued by an insurer or an agent, of what a policy looked like on the date it was printed. It names the insured business, the carrier, the types of coverage, the limits, and the dates the policy runs between. That is all it is asked to do, and within those limits it does it accurately.
A certificate’s limits are structural. It proves what was true on the day it was printed and says nothing about whether that policy is still in force on the day the saw actually runs. A certificate is a snapshot, not a live status, and that gap is where trouble hides. It is also an easy document to get wrong or misrepresent: a policy can lapse between printing and the job date, a certificate can be edited, or the business named on it can differ subtly from the one that shows up for the estimate.
Two mismatches are worth naming without resolving yet. The certificate’s name does not always match the business name on the quote — a parent company, a former trading name, or an owner’s personal name can appear instead. And the expiration date does not always sit past the scheduled work date, especially once a job slips by a week or two. Neither shows up from reading the certificate once; both show up with a phone call.
The Call that Confirms What the Paper Cannot
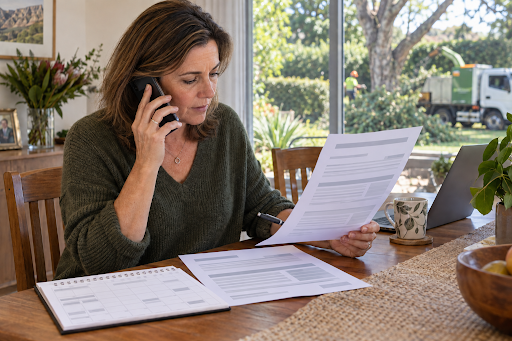
The call goes to the agent or carrier named on the certificate. A number on the contractor’s own letterhead only repeats what the contractor already claims; the insurer’s own line is what actually confirms it.
A handful of things get established on that call that the document alone cannot establish. The first is whether the policy is active today; the certificate itself only confirms the date it was printed. The second is whether the named insured matches the business quoted for the job, since a related entity trading under a similar name is a common mismatch. The third is whether the effective and expiration dates bracket the scheduled work date. The fourth is whether tree work is listed as a scheduled, covered operation, separate from general landscaping that excludes climbing and felling. The last is whether workers’ compensation genuinely extends to whoever does the climbing, or only covers office staff.
One step almost nobody takes is asking to be added as a certificate holder on the policy. That single request turns a one-time snapshot into ongoing information: if the policy lapses afterward, the insurer notifies the holder instead of leaving the homeowner to find out the hard way.
This verification is normally left entirely to the homeowner to carry out alone — the contractor hands over a document, and nobody else stands between that document and the checking. The certificate-holder request above works after a contractor is already booked; the same protection can also sit earlier in the process, folded into how a homeowner finds a contractor in the first place. A South African service that confirms a contractor’s liability insurance before any homeowner is handed a name works this way, with references checked alongside the cover.
What Your Own Policy Assumes About Your Choice
Choosing the contractor is something the homeowner does, and that choice carries consequences that surface only once a claim is filed. Where the crew’s own cover turns out to be absent or simply doesn’t apply to the loss, the damage moves to the homeowner’s own policy, bringing a deductible, a claims record, and a premium consequence attached to damage the homeowner did not cause and could not have prevented once the work was already underway.
Where an injured worker has no workers’ compensation behind him, attention can turn toward the homeowner’s own liability coverage as the only policy left standing. Homeowner policies also routinely treat work performed on the property by someone else differently from the ordinary perils they’re built around — a detail few people think to ask their own insurer about.
How any of this actually plays out depends entirely on the policy in question — coverage varies enough between insurers and states that nothing here should be read as a statement about a particular policy. A homeowner’s own insurer or agent is the place to confirm what theirs assumes, and the point to make that call is before a crew is booked.
Frequently Asked Questions About Hiring an Insured Tree Crew
How much liability insurance should a tree removal company have?
There isn’t a single figure that fits every job; the right amount is judged against the property’s actual exposure. A limit that comfortably covers a fence line does very little for a roof, and a policy sized for a small ornamental tree isn’t automatically sized for a large one standing within reach of a structure. The relevant comparison is the coverage against that specific property’s exposure, and a number quoted for a different job entirely says nothing useful about it.
What is a certificate of liability coverage?
It stands behind the contractor named on it, not behind the homeowner. An insurer or an agent issues it, and what it evidences is a single moment: the cover that contractor held on the day it was printed, on the terms recorded that day, for the business named on it and no other. Whether that same policy has run past that printed date and is still active today is a separate question, one a phone call to the issuer settles before work begins, not the certificate itself.
Do homeowners need liability insurance?
Most homeowner policies already include a liability component as a standard part of the coverage, separate from the part that covers the structure and its contents. That component is what can be asked to respond when someone other than the homeowner is hurt on the property, or when the homeowner’s own negligence causes a loss. Hiring a contractor whose own insurance is genuinely current and applicable is largely what keeps that component from being the policy that ends up answering for someone else’s work.
Conclusion
A certificate of insurance takes seconds to glance at and tells a homeowner very little on its own. The phone call that actually confirms what it claims takes only a few minutes and costs nothing, but the timing matters more than the content: it has to happen while there is still a choice to make. Once the work is underway, whichever policy was actually in force is the one that answers, and there is nothing left to verify and nothing left to change. Make the call while a different contractor is still an option.
©2026 The Dedicated House. All rights reserved. No part of this blog post may be used or reproduced without the written consent of the copyright owner.
Click the links below for any posts you have missed:
 Where Can I Buy Floor Scrubber Pads, Brushes, and Replacement Parts?
 Designing Premium Outdoor Spaces and Hardscapes
 The Remarkable Rise of Attic Conversions in Dublin: Understanding a Booming Industry
 A Practical Guide to Comparing Mountain Homes Before You Buy in Vail, Colorado
 Revitalizing Your Home with Professional House Painting Services
 Large Bedroom Wardrobe Planning: A Room-First Guide to Layout, Storage, and Daily Use
I’d love for you to join my email list! You’ll receive a notification straight to your inbox which will include links to my latest home project posts! Simply enter your address below.
Thanks for stopping by! Have a wonderful day/night depending on where you are in the world! Go with God and remember to be kind to one another!
Toodles,

Leave a Reply